
You leave your broker-dealer believing the separation was routine. Then you review BrokerCheck and find that the firm reported “Discharged”, accompanied by a narrative alleging policy violations. The next recruiting conversation changes immediately. A prospective firm wants an explanation, a regulator asks questions, and clients may discover the entry before you have a chance to provide context.
That's why U5 termination reasons deserve attention before, not after, a departure. Form U5 is a mandatory termination notice, and its reason for departure becomes part of the regulatory record maintained through FINRA's registration system. Depending on the entry and accompanying explanation, the filing can affect future employment, licensing discussions, client confidence, and the way every later compliance reviewer reads your history. Advisors evaluating a separation should also consider the broader employment questions addressed in this practical guide for brokers.
Why Your U5 Termination Reason Matters More Than You Think
A Form U5 isn't merely an administrative exit document. FINRA uses it, along with other registration information, to record why a registered person's association ended. For a full termination, the firm must select one of five fixed reasons, and the termination date and reason are required fields. The categories are Voluntary, Deceased, Permitted to Resign, Discharged, or Other (FINRA's Form U5 guidance).
The practical problem is that the form often becomes visible to people who weren't involved in the departure. FINRA Rule 8312 permits BrokerCheck to display the Reason for Termination reported in Section 3 of Form U5, and related U5 disclosure items can appear within three business days after FINRA processes the filing (FINRA Rule 8312). A disputed internal characterization can therefore become a public compliance and employment record before the advisor has completed a transition plan.
Career reality: The most damaging part of a U5 is often not the category alone. It's the combination of the category, the narrative, and the reader's lack of context.
Consider two advisors who leave after a compliance disagreement. One firm reports a voluntary resignation and gives a neutral explanation. Another reports “Permitted to Resign” while stating that the advisor departed during a review of alleged policy violations. The underlying facts may overlap, but the career conversation is entirely different. Future firms will usually focus on what the filing says, not what the advisor intended the departure to mean.
A difficult entry can also lead to state regulator inquiries, delayed onboarding, or additional questions during a registration transfer. It may affect how a recruiting firm evaluates a book of business and how clients react to a transition. The filing doesn't decide every outcome, but it changes the starting position.
The timing makes preparation critical. FINRA says the firm must file Form U5 within 30 days after employment ends and provide the departing person with a copy (FINRA registration guidance). Advisors who wait until after filing to think about the language may find that their negotiating power has narrowed sharply.
The Five FINRA Termination Reason Categories Explained
For a full termination, Form U5 requires the firm to select one of five categories. The selection should match the firm's actual reason for ending the registration, and some categories require a narrative explanation. The category is only the starting point. The wording that follows can shape recruiting discussions, registration reviews, and the advisor's ability to explain the departure later.
Voluntary
Voluntary generally means the advisor chose to leave. Common examples include accepting another opportunity, retiring, changing business models, or ending the association for personal reasons. The category is usually easier to explain than an involuntary termination, but it does not make the filing automatically harmless.
A firm may still provide a negative explanation when the circumstances require disclosure. If an advisor resigns during an investigation, for example, the narrative may describe the investigation or alleged conduct. The label may appear neutral while the accompanying explanation creates substantial career and licensing concerns.
Deceased
Deceased applies when the registered person's association ends because of death. It is an administrative classification, not a misconduct finding. The firm must still complete the filing accurately, but this category ordinarily does not create a career issue for the registered person.
Permitted to Resign
Permitted to Resign means the firm allowed the person to resign instead of formally discharging them. That distinction can affect how a future employer initially evaluates the record, but it should not be treated as a clean exit. FINRA requires an explanation when the firm selects Permitted to Resign, as described in the Form U5 instructions.
The narrative may refer to an investigation, alleged policy violations, supervisory concerns, or another issue that influenced the firm's decision. A receiving firm may view the category as less severe than Discharged, yet the explanation can still lead to detailed questions, document requests, or hesitation during onboarding.
Discharged
Discharged means the firm ended the association. Firms may use this category when they believe the advisor violated policy, failed to meet conduct expectations, or engaged in other behavior that justified termination. The firm must explain the selection.
The explanation must identify the reason without becoming argumentative or overstated. A short phrase such as “policy violation” may leave important questions unanswered. A longer narrative can create greater reputational exposure if it states inaccurate conclusions or presents allegations as established facts. That wording may later affect how the advisor explains the termination to prospective firms and regulators.
FINRA guidance also states that a firm terminating a registered person for misconduct must answer the related U5 misconduct disclosure question affirmatively, even when the firm did not originally make the allegations (FINRA Regulatory Notice 10-39). The firm's reporting responsibility therefore can extend beyond allegations that began inside the firm.
Other
Other applies when the separation does not fit the remaining categories. A branch closure, business restructuring, or merger may lead to this selection, depending on the circumstances. The firm must explain an Other selection.
The explanation can determine whether the entry reads as a business event or a conduct concern. “Business decision” communicates something different from wording that suggests compliance problems. Before the filing, an advisor may be able to seek a more accurate and neutral description of a business-driven departure. After submission, the advisor may need to request an amendment or pursue a formal dispute.
| Termination Reason | Typical Trigger | Narrative Comment Required? | Regulatory Risk Level |
|---|---|---|---|
| Voluntary | Advisor chooses to leave | Not automatically, but circumstances may require additional disclosure | Usually lower, unless the narrative raises concerns |
| Permitted to Resign | Firm allows resignation amid a concern or review | Yes | Higher |
| Discharged | Firm ends the association | Yes | High, depending on the explanation |
| Deceased | Death ends the association | Not a misconduct narrative | Generally administrative |
| Other | Circumstances that don't fit another category | Yes | Depends on the facts and wording |
Career and Licensing Consequences of Each U5 Entry
A U5 entry affects more than a résumé. BrokerCheck publicly surfaces the Reason for Termination, so recruiters, investors, and compliance personnel may review it when evaluating an advisor. A Voluntary or Other entry with neutral language may create little friction, while Discharged or Permitted to Resign can require a detailed explanation before a firm will proceed.
State regulators may also examine the entry during registration activity. An adverse filing can lead to follow-up questions, requests for documents, conditions on registration, or other scrutiny. The exact response depends on the facts, the jurisdiction, and the surrounding record. No category guarantees approval or denial, but some entries plainly create more work for the advisor and the receiving firm.
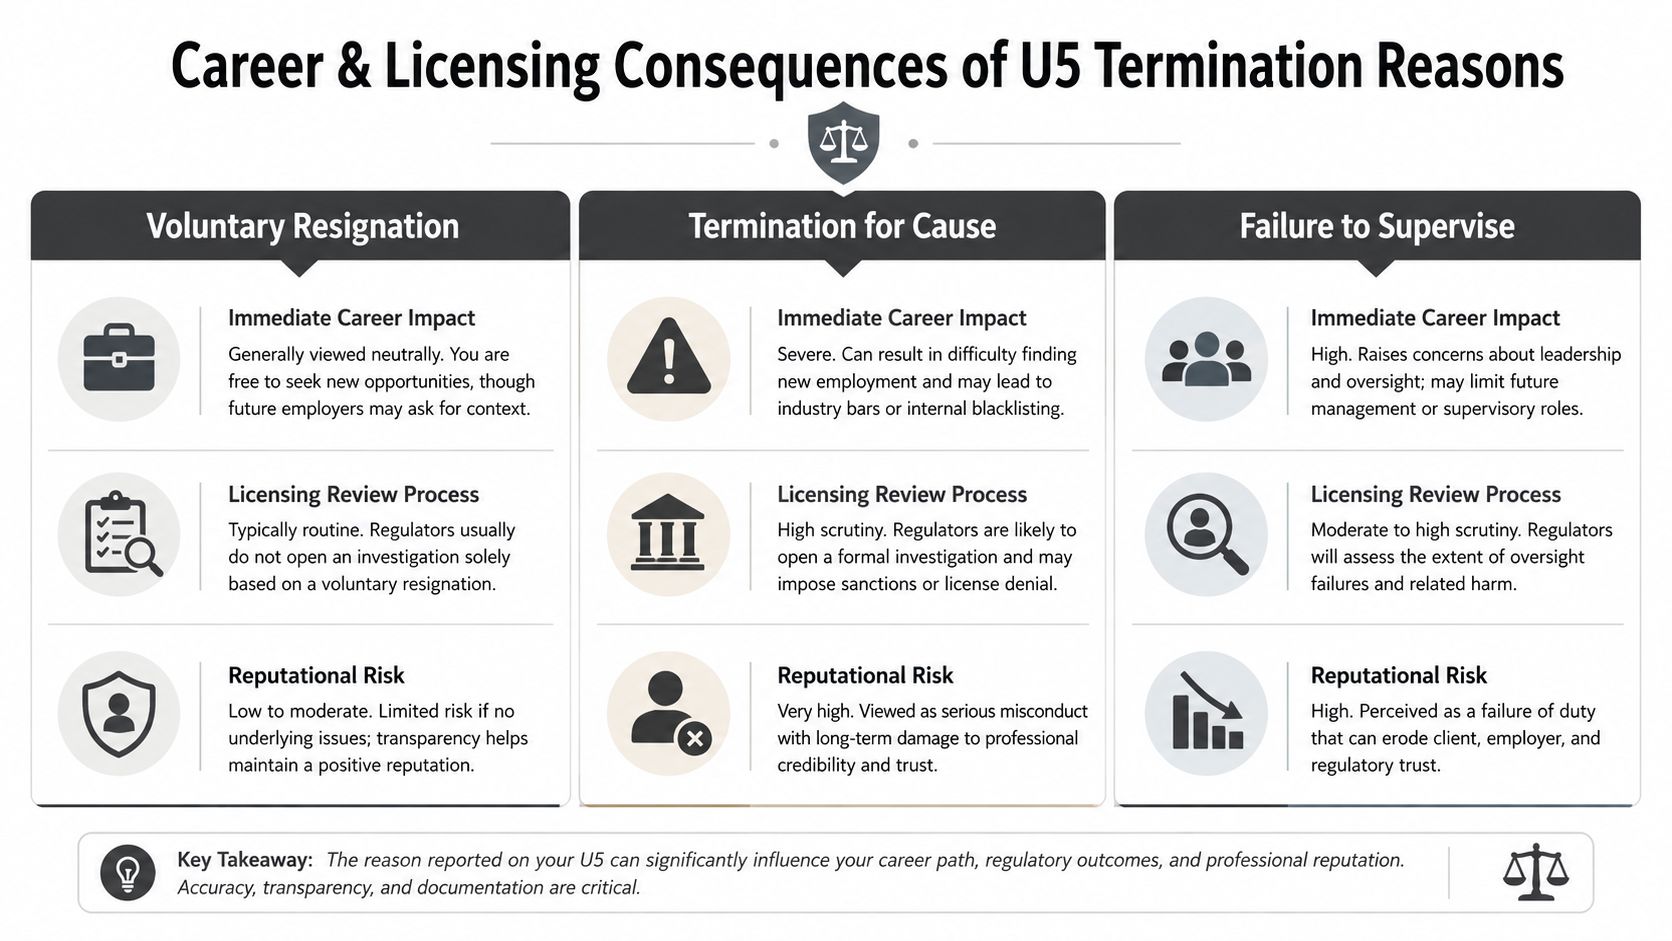
How the categories compare in practice
Voluntary is usually the easiest category to explain, provided the accompanying information is neutral and accurate. Other can also be manageable when it reflects a merger, closure, or business decision rather than personal conduct.
Permitted to Resign and Discharged create a different recruiting environment. A receiving firm may ask for the full termination explanation, related correspondence, internal findings, and the advisor's account. Some firms may decide not to proceed before an interview because they view the filing as a compliance risk.
A negative entry can also affect commercial relationships. Clients may ask why the advisor left, whether the firm found wrongdoing, and whether their accounts are safe. The advisor must answer those questions carefully, without making unsupported statements or violating separation obligations.
Advisors facing a serious disclosure should understand how U5 issues can intersect with broader regulatory concerns, including the issues discussed in this overview of FINRA statutory disqualification. A U5 doesn't automatically create statutory disqualification, but it can become part of a larger regulatory review.
How to Respond to or Amend a Damaging U5 Filing
The best response begins before the filing. FINRA gives the firm 30 days after employment ends to file Form U5 and provide a copy to the departing person (FINRA registration guidance). That period is short, especially if the advisor is negotiating separation terms, moving client relationships, and preserving evidence at the same time.
Start with an informal amendment request
Review the filed form line by line. Compare the reason, termination date, disclosure answers, and narrative with emails, performance records, investigation materials, and the separation agreement. If the filing is incomplete or inaccurate, send a written request to the firm's compliance or legal department.
A strong request doesn't say, “This is unfair.” It identifies the specific sentence, explains the factual error, provides supporting documents, and proposes replacement language. The firm may agree to amend the filing, but the request should assume that the firm will evaluate risk, privilege, and regulatory obligations before changing its position.
Form U5 is not static. FINRA's amendment form allows firms to update disclosure items, the termination date, the reason for termination, and residential information (FINRA Form U5 amendment form). That creates a route for correction when new facts emerge, though it doesn't guarantee that a firm will use it.
Protect your position while the dispute continues
An advisor may submit a Form U4 addendum comment to provide a professional response while the dispute remains unresolved. The comment should be factual, concise, and free of admissions that could be used against the advisor. It won't erase the firm's filing, but it can give readers context.
Preserve evidence immediately. Keep the original U5, all versions of the narrative, relevant policies, performance reviews, investigation notices, meeting notes, text messages, and emails. If the dispute involves a termination letter or separation agreement, practical documentation principles discussed in this resource on how to reduce contractor risk can help frame the importance of a clear written record, even though the regulatory setting is different.
Consider arbitration and formal relief
If informal discussions fail, counsel can assess a FINRA arbitration claim and the appropriate remedy. A Statement of Claim should identify the challenged language, explain why it is inaccurate, and connect the requested relief to the applicable FINRA standards. The advisor must build the case with evidence and witnesses, not just disagreement with the firm's judgment.
The materials provided for U5 disputes often refer to narrow expungement standards, including information that is factually impossible, clearly erroneous, or defamatory. Those standards require careful legal analysis, and the proper rule may depend on the type of disclosure and the relief sought. A BrokerCheck comment is a stopgap. It's not a substitute for an amendment, arbitration award, or other legally appropriate remedy.
For a focused discussion of the filing itself, advisors can review this guide to Form U5 and FINRA issues. Counsel should also evaluate any arbitration clause, contractual deadline, defamation theory, and state notification obligation before the advisor chooses a path.

Common Misconceptions About U5 Termination Reasons
Advisors sometimes treat a U5 filing as an internal HR record. That assumption can create career problems. Form U5 connects employment history with registration, public disclosure, and regulatory supervision, so the termination category and attached explanation both matter.
Myth one, voluntary always means safe
A voluntary resignation may be easier to explain than a discharge, but “voluntary” does not neutralize unfavorable wording. A narrative such as “resigned amid allegations of policy violations” sends a different message from “resigned to pursue another opportunity.”
Review the category, every sentence in the narrative, and how the entry could affect recruiting, registration reviews, and future disclosure discussions.
Myth two, the firm will fix mistakes out of goodwill
A firm may amend a filing when evidence supports correction, but an objection alone rarely produces a change. Compliance staff must consider reporting duties, supporting records, and legal exposure.
Make a focused request. Identify the precise error, attach documents, propose accurate language, and explain why the amendment remains consistent with the firm's obligations. Emotional accusations can make internal approval harder.
Myth three, future employers will not look
BrokerCheck can display the Reason for Termination and related U5 disclosures after FINRA processes them under Rule 8312. Recruiters and compliance officers may encounter the entry during ordinary diligence. Treat the filing as public-facing from the outset, because its wording can influence hiring decisions and regulatory questions long after the departure.
Myth four, arbitration is automatically pointless
Arbitration is not guaranteed to change a U5, and the advisor must satisfy the applicable legal and regulatory standards. Still, doing nothing leaves a damaging entry in place while it continues to affect recruiting and regulatory reviews.
A well-supported dispute may create an opportunity for correction, settlement, or formal relief. The advisor should compare the cost, available evidence, contractual requirements, and likely career impact before choosing a response.

Practical Checklist and Sample Language for Advisors
A U5 dispute often turns on wording. Use precise, document-supported language, and keep each communication suitable for later review by compliance personnel, regulators, arbitrators, or a prospective employer.
Before separation
- Set the communication record: Use a clear subject line such as “Request for review of proposed Form U5 language”. Send the request through a channel that preserves delivery and attachments.
- Identify the exact entry: Quote the proposed termination reason and narrative. Separate factual errors from disagreements about characterization.
- Propose replacement text: Offer language that states the verified reason for separation without unnecessary conclusions. Explain how the wording fits the firm's reporting obligations.
- Protect permitted records: Keep employment documents, performance reviews, relevant emails, and meeting notes that you may lawfully retain. Do not take customer information or other firm-confidential material.
- Set a response date: Ask for written confirmation before the planned filing date. If the firm refuses to engage, escalate through the appropriate compliance or general counsel channel rather than sending repeated informal messages.
Sample language
Request for amendment or pre-filing review
Subject: Request for review of proposed Form U5 language
I request review of the proposed Section 3 termination reason and narrative. The statement that “[quote the disputed language]” is inaccurate because [specific factual explanation]. Attached are [identified documents], which support the following proposed language: “[accurate replacement text].” Please confirm whether the firm will use this language or provide its factual basis for the proposed entry.
Demand to general counsel
Subject: Form U5 accuracy and record preservation
The proposed Form U5 narrative contains a material factual error concerning [specific issue]. The attached records show [ concise fact]. Please preserve records relating to the investigation, separation, and filing, and confirm whether the firm will correct the narrative before submission. I request a written response by [stated date].
BrokerCheck comment
I dispute the firm's characterization of my departure. The reported information is inaccurate as to [specific point]. The relevant records support [brief accurate fact]. I am pursuing review through the available process and reserve my rights concerning the filing and related statements.
A comment should correct the record without arguing every disputed detail, accusing individuals, or revealing confidential information. The strongest version states the disputed point, gives the neutral fact, and identifies the review status.
After filing
Create a dated file index, not just a chronology. Label each document by date, author, recipient, and issue, then identify witnesses whose testimony matches contemporaneous records. Use a subject line such as “Request for correction of filed Form U5” for later correspondence, and keep communications professional.
Before sending a demand, have counsel check whether the proposed language creates admissions or conflicts with prior statements. A short, factual message is easier to defend than an angry text or broad allegation.
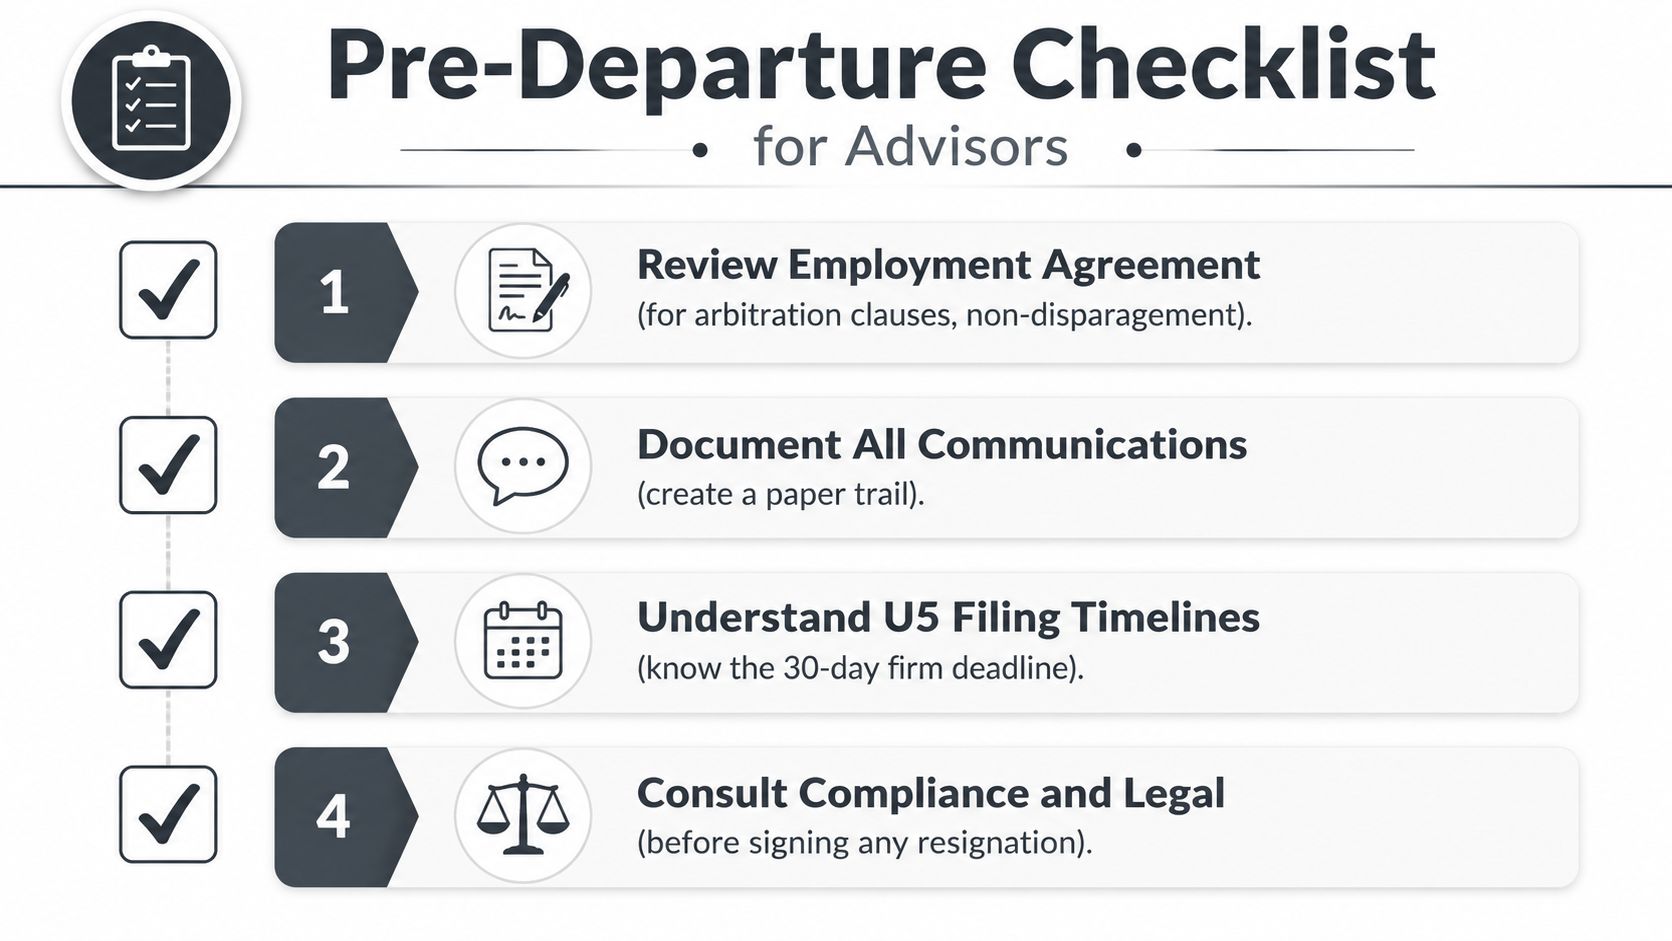
Protecting Your Career with Experienced Legal Counsel
A poorly worded U5 termination reason can follow an advisor through recruiting, licensing, and client diligence. The narrowest window for negotiating accurate, neutral language is usually before separation and before the firm submits the form. After filing, the advisor may still have amendment, comment, arbitration, or other remedies, but each requires a more deliberate strategy.
Don't sign a resignation letter, release, separation agreement, or UDR consent form without understanding how it may interact with the firm's U5 filing. Experienced regulatory compliance counsel can help assess the proposed language, preserve evidence, request an amendment, prepare an arbitration claim, and address communications with regulators or a prospective firm.
The firm's HR department and in-house counsel represent the firm. They aren't your personal advocates. Independent advice can help you negotiate a defensible departure record before the language becomes public and harder to change.
If you want to discuss your business law matter, contact Kons Law at (860) 920-5181. Kons Law advises financial advisors and brokerage professionals on Form U5 disputes, employment separation issues, regulatory inquiries, and securities arbitration. Visit Kons Law to arrange a consultation about protecting your professional record.
