You're already in the worst part of the process. A disclosure has been flagged, compliance is asking questions, and someone has probably said the word “statutory disqualification” in a tone that made your stomach drop. If that's where you are, stop guessing. The wrong move now is treating this like a routine form correction, because FINRA statutory disqualification can turn a career issue into a licensing wall almost overnight.
The hard truth is simple. Once a triggering event exists, the question is no longer whether the matter is uncomfortable. The question is whether you're still eligible to associate with a FINRA member firm, and if not, whether a sponsoring firm is willing to fight for relief through an Eligibility Proceeding.
When a Career-Defining Disclosure Lands on Your Desk
A registered representative usually feels the shift before the paperwork catches up. One day you're answering ordinary compliance questions, and the next day a Form U4 amendment, a criminal disclosure, or a regulator's request for information makes your file look very different. The brokerage firm doesn't need to call it statutory disqualification for the problem to exist, because the status follows the event itself, not the label.
At that point, your working life changes fast. A person who can't associate with a FINRA member without approval generally can't just keep doing business as usual, and the firm's risk team will treat the matter as a gatekeeping issue, not a coaching moment. If a broker-dealer thinks the event is disqualifying, it will often freeze new activity, scrutinize the rep's continuing authority, and decide whether to sponsor relief or cut ties.
Practical rule: If a disclosure event looks disqualifying, assume every document, text message, and email will matter later.
The best advisors don't ask, “How bad is the headline?” They ask, “What category is this event, what did the form require, and who is willing to sponsor relief?” That's the right frame because FINRA statutory disqualification turns on specific triggering events, form accuracy, and the firm's appetite for an MC-400 filing.
For a focused intake checklist before you speak to compliance, use these questions to ask a broker. The three issues that matter most are the same ones I see in every serious file, what triggered the status, what it does to the license, and whether relief is realistically available.
What FINRA Statutory Disqualification Actually Means
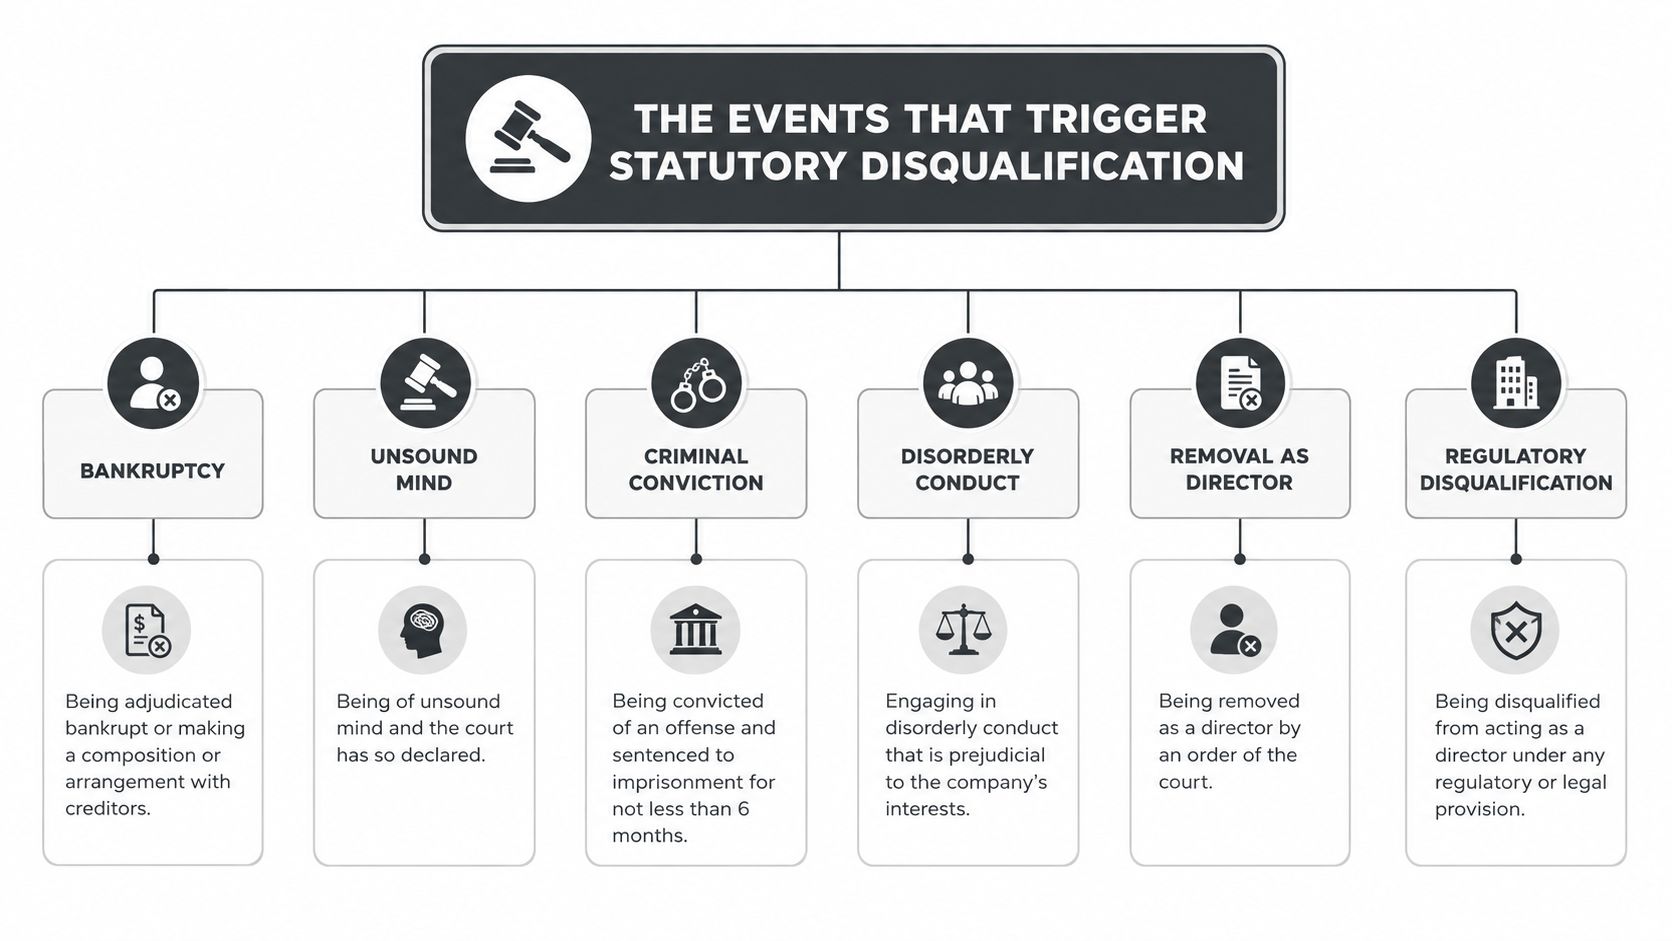
Statutory disqualification is not the same thing as an ordinary fine, suspension, or written warning. It is a legal status that can keep a person out of the securities industry unless FINRA grants permission for the association. FINRA's published eligibility guidance makes that point bluntly, a statutorily disqualified person generally cannot associate with a FINRA member unless FINRA approves the relationship first. FINRA's eligibility requirements spell out the categories that trigger this result.
The status originates in the Exchange Act framework, and FINRA has said the law was broadened in 1991 to include new domestic and foreign criminal and civil offenses, including any U.S. felony conviction within the prior 10 years. That expansion matters because it made the category broader and more durable than most advisors expect. If you are inside the triggering class, the industry sees it as a licensing problem, not just an enforcement record.
The legal effect that matters
The practical effect is severe. A person who's statutorily disqualified generally can't work for a FINRA member in any capacity that requires association unless there's prior approval. That means the issue is not limited to selling securities or managing accounts, it reaches the ability to remain attached to the firm at all.
For perspective on how legal authority sits next to digital visibility, Magnitude Marketing finance SEO is a useful resource on how financial businesses present themselves online. The analogy is useful here too, because in regulated finance, one underlying event can shape the entire public and professional record.
FINRA also lists findings that a person “willfully” violated federal securities or commodities laws, MSRB rules, or failed to supervise another violator as disqualifying events. That is why the status is so unforgiving. It is built to block access first and ask follow-up questions later.
The Events That Trigger Statutory Disqualification
A disclosure hits the file. A branch manager asks whether the person can stay on the books. That is the moment to sort FINRA statutory disqualification by buckets, because the category controls whether the firm is dealing with a licensing problem, a disclosure problem, or both.
Criminal, regulatory, SRO, and conduct-based triggers
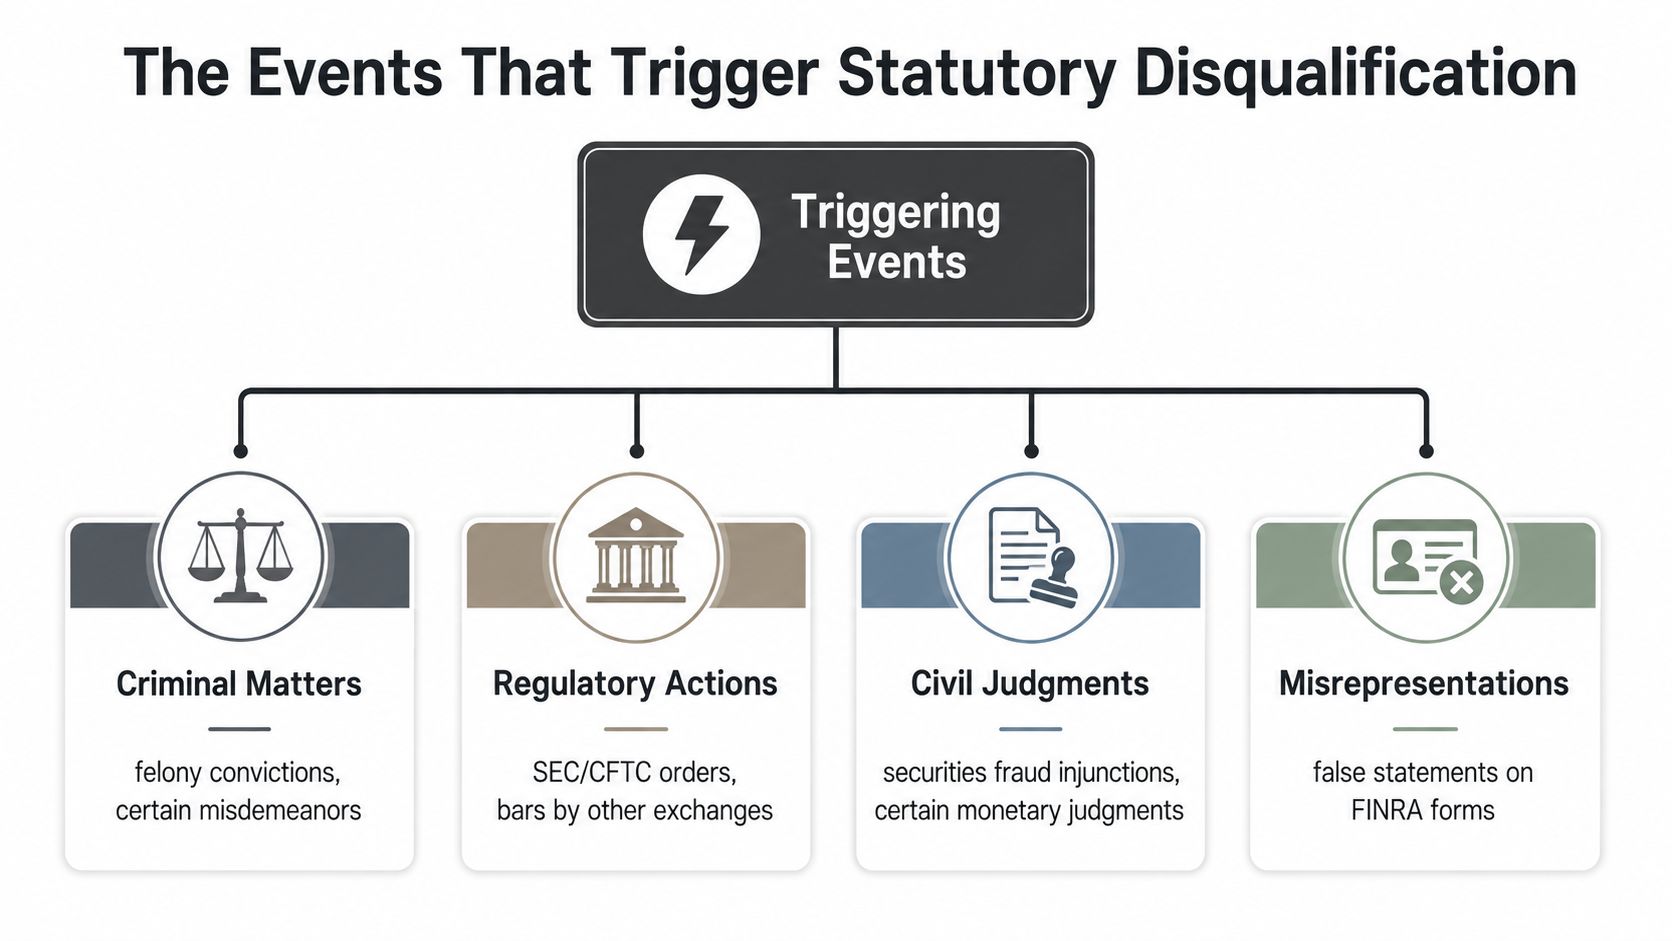
The first bucket is criminal. FINRA's eligibility standards cover certain misdemeanor convictions and all felony convictions for a period of 10 years from the date of conviction. That 10-year window is a hard gate in the framework. FINRA's eligibility requirements also make clear that the criminal category can reach both domestic and foreign matters.
The second bucket is regulatory and civil action. Permanent or temporary injunctions involving securities-related misconduct, SEC/CFTC bars, registration denials, and registration revocations all sit in the danger zone. FINRA treats these matters as serious because another regulator has already decided the person should not be trusted without controls.
The third bucket is SRO action. Expulsions or bars from FINRA, another self-regulatory organization, or a foreign equivalent can trigger the status. Advisors often downplay this bucket because it reads like an administrative record, but FINRA treats it as a licensing problem with real consequences.
The fourth bucket is conduct-based findings. FINRA's 2009 notice explains that the revised definition added willful violations of federal securities or commodities laws, Sarbanes-Oxley grounds, and associations with certain other disqualified persons. FINRA Regulatory Notice 09-19 lays out that expansion in FINRA's own words.
The mistake I see most often is simple. People fixate on convictions and miss the rest of the trigger list. FINRA's list reaches conduct that never produced a criminal judgment.
A practical checklist helps:
- Convictions: Felonies, and certain securities-related misdemeanors, especially within the 10-year window.
- Regulatory bars and denials: SEC, CFTC, and comparable foreign orders.
- SRO discipline: FINRA bars, expulsions, and foreign equivalent actions.
- Willful findings: Intentional violations and related conduct findings that FINRA has identified as disqualifying.
For the disclosure side, the discipline around handling workplace misconduct is a useful parallel. Once the underlying conduct is serious enough, the reporting, supervision, and employment consequences spread fast.
How Disqualification Shows Up on Form U4 and Form U5
The forms are where the legal status becomes operational. Form U4 is the registration form that captures criminal, regulatory, and civil disclosures, and a “Yes” answer immediately tells the firm to dig deeper. That review is not optional. It is the point where the firm decides whether the person can remain registered, whether disclosure is complete, and whether the issue might ripen into a FINRA statutory disqualification problem.
A bad answer on Form U4 can create a second problem. If the disclosure was incomplete, misleading, or false, the filing issue itself can become a separate basis for discipline, and in some cases, a separate disqualifying event. That is why sloppy amendments are so dangerous. A rep who tries to manage the optics instead of the facts often creates a second file that is worse than the first.
Where the forms actually meet the problem
Form U5 matters when the relationship is ending. A termination disclosure can trigger its own fight over the reason for separation, the wording of the filing, and any later amendment. For a broader discussion of that process, see this Form U5 resource.
| Trigger Category | Form U4 Question | Typical Review Window |
|---|---|---|
| Criminal matters | Felony and specified misdemeanor questions | Immediate compliance review after disclosure |
| Regulatory actions | Questions on bars, denials, suspensions, and revocations | Immediate review and possible document request |
| Civil matters | Questions on injunctions and similar civil matters | Immediate review once the event is reported |
The table above is the practical map. If the answer is yes, the firm is no longer just updating a file, it's deciding whether the rep can stay attached to the business at all.
A disclosure event on U4 also tends to pressure the current employer. Most member firms will not sponsor a statutorily disqualified person without an approved MC-400 in hand, and many won't even discuss continued association until the file is fully documented. That is why the issue often feels like a termination even before the final employment decision is made.
For a deeper firm-side perspective, this FINRA member firm resource is useful context. The sponsor is the gatekeeper, and without the sponsor, the relief process usually goes nowhere.
The Eligibility Proceeding and How FINRA Approves Relief
The main remedy is FINRA's Eligibility Proceeding under the 9520 series. For an individual, the sponsoring firm usually files Form MC-400. For a firm applicant, it uses Form MC-400A. That's the mechanism. There isn't a shortcut that makes a serious disqualifying event disappear.
The paperwork has to be assembled with discipline. FINRA's guidance says a disqualified firm notified by RAD after an SEC order must file MC-400A within 10 business days if it wants to seek continued membership, and the submission should include the order, a written justification, designated form responses, and usually a plan of heightened supervision. FINRA's FAQ on eligibility proceedings is explicit about those ingredients.
What gets the case moving
An uncontested matter can be processed through FINRA's Department of Member Regulation, while a contested one can escalate to a Hearing Panel and then the National Adjudicatory Council. That's where the tone changes. At that point, the file is no longer about mere registration, it's about whether FINRA trusts the sponsor's controls enough to let the association continue.
If the sponsor can't explain the controls in plain English, FINRA won't assume the controls are good enough.
An effective package does three things well. It shows the underlying order or event clearly, it explains why continued association serves the public interest, and it proves the firm's supervision will change behavior. A generic “we'll watch him closely” memo usually fails because it doesn't show structure.
A disqualified person should also understand the practical timing. An MC-400 is usually a precondition for staying with the current firm and for getting hired elsewhere. Until the application is in play, the market often treats the advisor as effectively unplaceable.
The Five Factors FINRA Weighs in Every Waiver Request
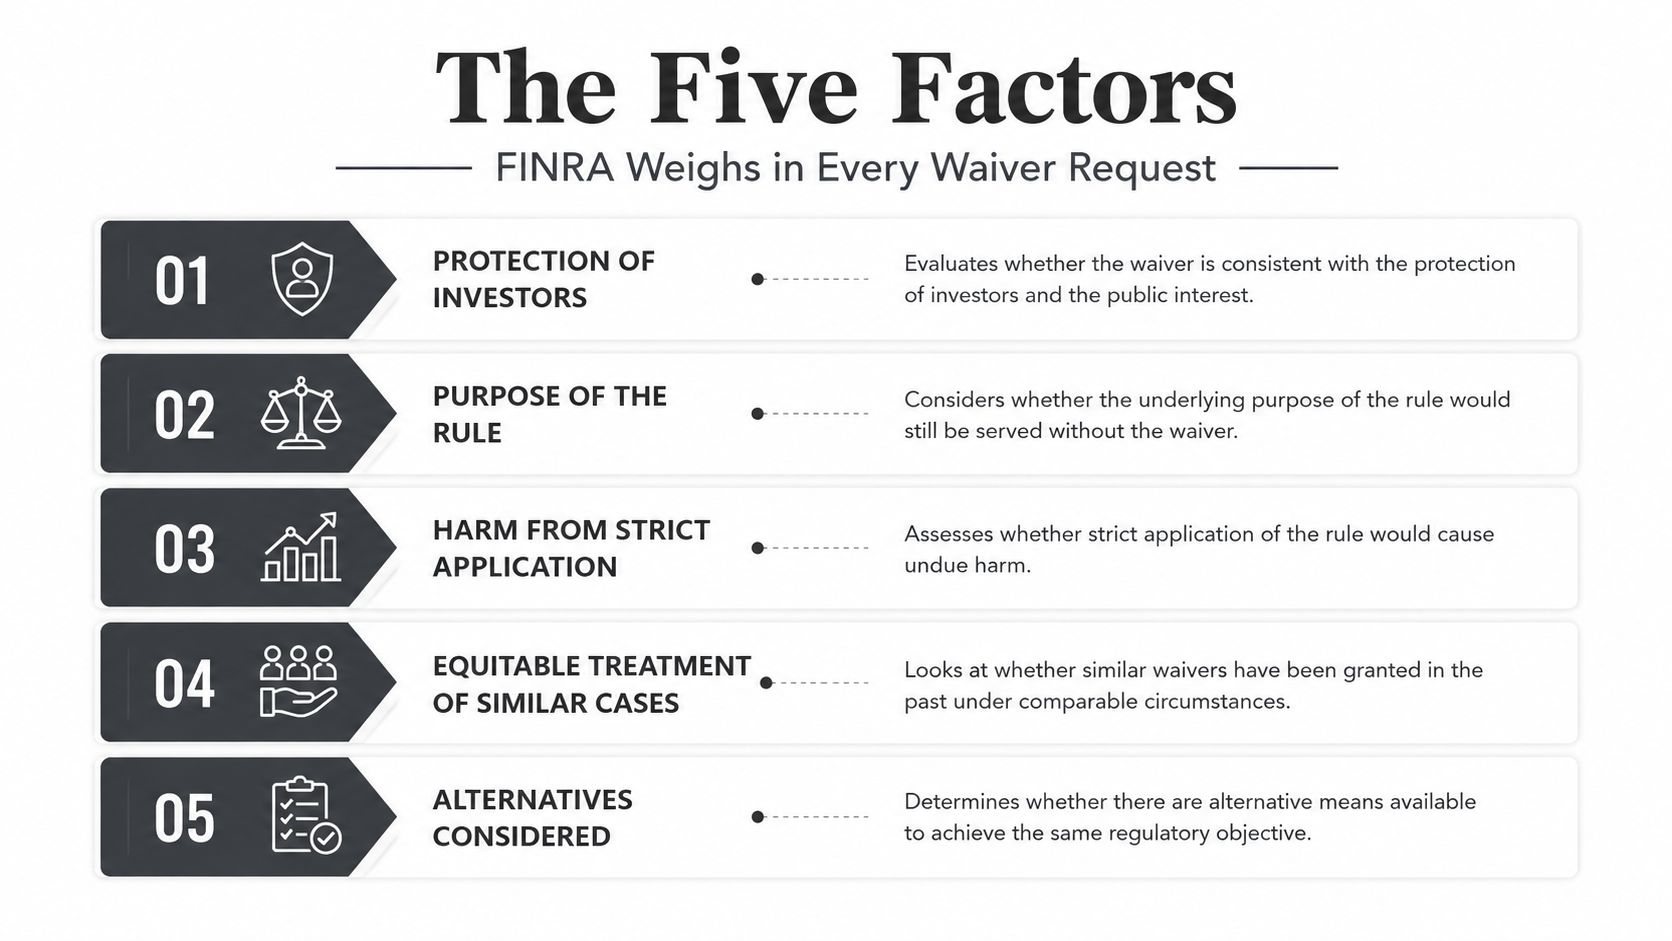
FINRA does not decide these cases by instinct. It looks at the underlying facts through a risk lens, and the five core factors are the ones that matter most: nature of the misconduct, time elapsed, disciplinary history, level of supervision, and how closely the proposed role relates to the conduct. Those are the pressure points, and each one can move the outcome.
How each factor helps or hurts
The nature of the misconduct is usually the first filter. A single, older issue with a narrow fact pattern is a very different case from a record that suggests dishonesty, disregard for supervision, or client harm. FINRA is much less forgiving when the conduct goes to the heart of trust, and it should be.
Time elapsed matters because regulators want to know whether the event is ancient history or recent behavior. Old conduct can be manageable when the file also shows stability and clean supervision, but recent conduct is hard to explain away. The shorter the distance between the event and the application, the more skeptical the review usually becomes.
Disciplinary history tells FINRA whether this was a one-off or part of a pattern. Multiple prior events make it much harder to argue that the person is now a controlled, lower-risk association. A clean history, by contrast, gives the sponsor something concrete to point to.
Supervision is where most applications succeed or fail in practice. If the firm proposes a real plan, with written checks, manager sign-off, and meaningful account review, the case looks better. If the supervision plan is vague, the waiver request looks performative, not protective.
Role proximity is the sleeper issue. If the proposed job puts the person back into the same kind of client-facing or supervisory position that created the problem, FINRA will notice. A narrower, more controlled role is usually easier to defend than a role that recreates the original risk.
For another example of how formal waivers are judged in high-stakes settings, waivers for DUI offenders joining the military shows the same basic principle, the decision turns on the facts, the controls, and the credibility of the applicant's plan.
The best applications usually combine older conduct, no repeat history, a disciplined supervision model, and a limited role that doesn't recreate the original exposure. The worst ones combine recent conduct, repeat problems, and a request to put the person right back where the risk started.
Defense Strategy and Immediate Steps for Impacted Advisors
The first move is documentation. Save the Form U4 history, the U5 drafts, every email from compliance, the 8210 letter, and every version of your written explanation. If you don't preserve the record early, the sponsor and regulator will build the narrative without you.
The second move is controlled communication. Respond to Form U4 amendments carefully, don't over-explain in a way that creates new inconsistencies, and never treat an 8210 request like a casual back-and-forth with HR. Those responses become the file FINRA reads later, and they're often more important than the underlying event.
The choices that usually decide the case
You also need to decide whether the current firm is a sponsor or a dead end. Some firms will file an MC-400 if the file is manageable, but many won't. If the sponsor won't stand behind the application, you should assume you'll need to line up another sponsor willing to carry the application through.
The separation agreement matters more than most advisors realize. The wording around resignation, termination, and amendment timing can shape the Form U5 record and influence later arguments about why the relationship ended. That is not a detail to leave to a rushed exit process.
Parallel exposure is another trap. The same conduct can sit in front of FINRA, the SEC, a state securities regulator, and, for some advisors, the CFP Board. If you ignore one forum while fighting another, you'll create inconsistent statements that hurt all of them.
Don't wait for a Wells submission to hire counsel. By then, the record is usually already tilted against you.
The effective mitigation presentation is direct, factual, and complete. It identifies the event, explains the corrective steps, shows the supervision plan, and avoids self-serving language that sounds like denial. That's the posture regulators trust.
Next Steps and When to Call a Securities Defense Lawyer
FINRA statutory disqualification is automatic, personal, and technical. It follows the person, not the firm, and it doesn't vanish just because the underlying matter feels old or resolved. Relief is possible, but only if the sponsor, the forms, and the supervision plan line up the right way.
If you're dealing with a disclosure, an 8210 request, a U4 or U5 fight, or a possible MC-400 filing, get counsel involved before the file hardens. For more on that, see this regulatory compliance attorney resource.
If you want to discuss your business law matter, contact Kons Law at (860) 920-5181. The firm represents advisors in FINRA inquiries, 8210 defense, securities arbitration, and CFP Board disciplinary matters across more than 25 states, and it knows how these files get decided.
If you're facing a FINRA disclosure issue, an eligibility proceeding, or a broker-dealer termination tied to a disqualifying event, Kons Law can help you get organized fast and protect the record before it gets worse. Visit Kons Law to discuss your matter confidentially and get a clear strategy for the next move.
