An investor discovers trades they never authorized. A financial advisor receives a termination letter and realizes the wording may follow them through the industry on Form U5. In both situations, the first reaction is usually the same: preserve the records, identify who may be responsible, and determine where the dispute must be filed.
For many brokerage and industry employment disputes, that forum is securities arbitration. FINRA's forum handled 2,469 new securities arbitration filings in 2024, including customer and intra-industry matters, and closed 3,108 cases that year. The average turnaround was 12.5 months, and 84% of customer cases closed through settlement or paid damages. These figures show why arbitration is not a niche alternative. It's a central dispute-resolution channel for investors, brokers, advisors, and firms. FINRA's published arbitration statistics provide useful context for the forum's current scale and resolution pattern.
When a Securities Dispute Lands on Your Desk
The first seventy-two hours after a dispute surfaces can matter more than the next several months of argument. An investor should preserve account statements, trade confirmations, emails, text messages, portal messages, and notes of conversations with the broker. An advisor should secure the termination notice, employment agreement, compensation records, compliance communications, customer complaints, and prior versions of any Form U5 language.
The immediate legal question is not just whether someone acted improperly. It's which agreement controls the dispute. Brokerage account agreements commonly contain predispute arbitration clauses, while financial industry employment contracts often direct disputes to FINRA, AAA, JAMS, or another forum. That clause can affect the applicable rules, arbitrator-selection process, discovery limits, filing mechanics, and whether a court action is available at all.
Practical rule: Don't let the other side's first description of the dispute become the official record. Preserve the documents before anyone edits, deletes, or overwrites them.
The people involved may have very different objectives:
- Retail investors may be focused on unauthorized trading, unsuitable recommendations, losses, excessive activity, or misleading statements.
- High-net-worth clients may be concerned with complex products, private investments, concentrated positions, or damages that require complex valuation.
- Financial advisors and registered representatives may need to defend a Form U5, pursue unpaid compensation, challenge a promissory note, or address wrongful termination.
- Small firms and broker-dealers may be balancing defense costs, regulatory exposure, customer relationships, and the risk of an adverse award.
The forum clause should be reviewed alongside the claim's dates. FINRA's eligibility rule generally bars arbitration when six years have passed from the occurrence or event giving rise to the claim. FINRA Rule 12206 is not a deadline to discover after the fact. It's a threshold issue that can decide whether the forum will hear the matter.
Regulatory inquiries create a separate track. A securities arbitration claim is not the same as an SEC investigation or a FINRA enforcement matter, although the same documents and conduct may appear in both. Advisors and firms facing that overlap should understand the difference between private recovery, employment protection, and regulatory defense, including the issues discussed in SEC investigations and enforcement matters.
What Securities Arbitration Actually Is
Securities arbitration rests on three legal layers. The first is the predispute arbitration agreement in a customer, employment, partnership, or commercial contract. The second is the sponsoring forum's procedural framework, such as FINRA's Code of Arbitration Procedure. The third is the Federal Arbitration Act, which generally supports enforcement of valid arbitration agreements and limits the grounds for overturning an award.
That structure produces a process that differs from court litigation in ways that affect strategy:
| Dimension | Securities Arbitration | Court Litigation |
|---|---|---|
| Decision-maker | One arbitrator or a panel, often with relevant commercial or securities experience | Judge, and sometimes a jury |
| Discovery | Usually narrower and controlled by forum rules and panel orders | Governed by court rules, often broader |
| Confidentiality | Proceedings are generally less public than court cases | Filings and hearings are commonly public |
| Speed | Compressed schedules can move a case faster | Court calendars may create longer delays |
| Appeal or review | Vacatur is available only on limited legal grounds | Broader appellate review may be available |
| Class claims | Usually individual claims, subject to contract and jurisdictional issues | Class procedures may be available under court rules |
FINRA arbitration itself is not one universal procedure for every claim. A customer dispute, an intra-industry compensation case, and a request involving a Form U5 may raise different pleading, eligibility, panel, and evidentiary questions. The agreement and the facts determine which provisions matter.
A FINRA panel also isn't a government regulator. The arbitrators decide the private dispute submitted to them. They don't issue the same type of enforcement order that the SEC or FINRA's Department of Enforcement might seek, and the claimant must prove the private causes of action and damages at issue.
The process is also generally not a class proceeding. Arbitration clauses often require individual claims, and class waivers can create serious barriers to aggregation. Whether a waiver applies can depend on the contract, the parties, and the governing law, so the clause should be analyzed before filing a broad complaint.
The practical point is simple. Arbitration isn't merely court litigation in a different room. It rewards disciplined issue selection, early document control, concise damages analysis, and careful presentation to the decision-maker who will hear the case.
Choosing Between FINRA, AAA, and JAMS
Forum selection starts with the contract, not with personal preference. A registered representative's employment agreement may require FINRA arbitration, while a separate business agreement may name AAA or JAMS. A customer's account agreement may also contain provisions that affect whether a claim belongs in FINRA's forum.
FINRA Dispute Resolution is usually the natural forum for customer-broker disputes and many intra-industry matters involving employment, compensation, promissory notes, and Form U5 issues. FINRA rules address securities-industry relationships directly, and its arbitrator rosters include neutrals familiar with brokerage operations, supervision, products, and industry compensation structures. The forum's fees, filing categories, ranked-list arbitrator selection, and discovery rules shape the case from the beginning.
AAA may be the right forum when a contract selects the American Arbitration Association's employment, commercial, or securities procedures. It can appear in disputes outside FINRA's mandatory industry coverage, including certain business-to-business and franchise-related matters.
JAMS is often selected for complex commercial disputes involving parties, customized procedures, or a preference for a more flexible case-management structure. It may be appropriate when the contract permits customized discovery, specialized arbitrator selection, or a hearing design.
| Criterion | FINRA | AAA | JAMS |
|---|---|---|---|
| Mandatory coverage | Common for FINRA member and associated-person disputes | Depends primarily on contract language | Depends primarily on contract language |
| Panel expertise | Strong securities-industry orientation | Varies by roster and case type | Varies, with options for specialized commercial neutrals |
| Discovery | Governed by FINRA rules and panel orders | Governed by selected AAA rules and arbitrator orders | Governed by selected JAMS rules and case-management orders |
| Fees | FINRA filing, forum, and hearing fees apply | AAA administrative and arbitrator fees apply | JAMS administrative and arbitrator fees apply |
| Flexibility | Structured securities procedures | Procedure depends on selected rules | Often adaptable for complex commercial cases |
| Timeline | Driven by FINRA scheduling and panel availability | Depends on administrator and arbitrator | Depends on administrator and arbitrator |
A quick decision sequence works better than arguing over which brand is generally preferable:
- Read the predispute clause and every incorporation by reference.
- Confirm whether FINRA rules apply because of the parties' industry relationship.
- Identify the claim type, requested relief, governing law, and likely discovery burden.
- Compare fee exposure, arbitrator qualifications, and scheduling needs.
- Check whether the selected forum can grant the relief sought.
If a hearing involves multilingual witnesses or documents, accurate interpretation can affect credibility and the evidentiary record. Counsel may find confidential arbitration language support useful when planning interpretation for a private proceeding.
A practical explanation of the filing and panel process is also available in this overview of the FINRA arbitration process. The governing clause remains the starting point, because filing in the wrong forum can create avoidable delay and motion practice.
The Arbitration Lifecycle From Filing to Award
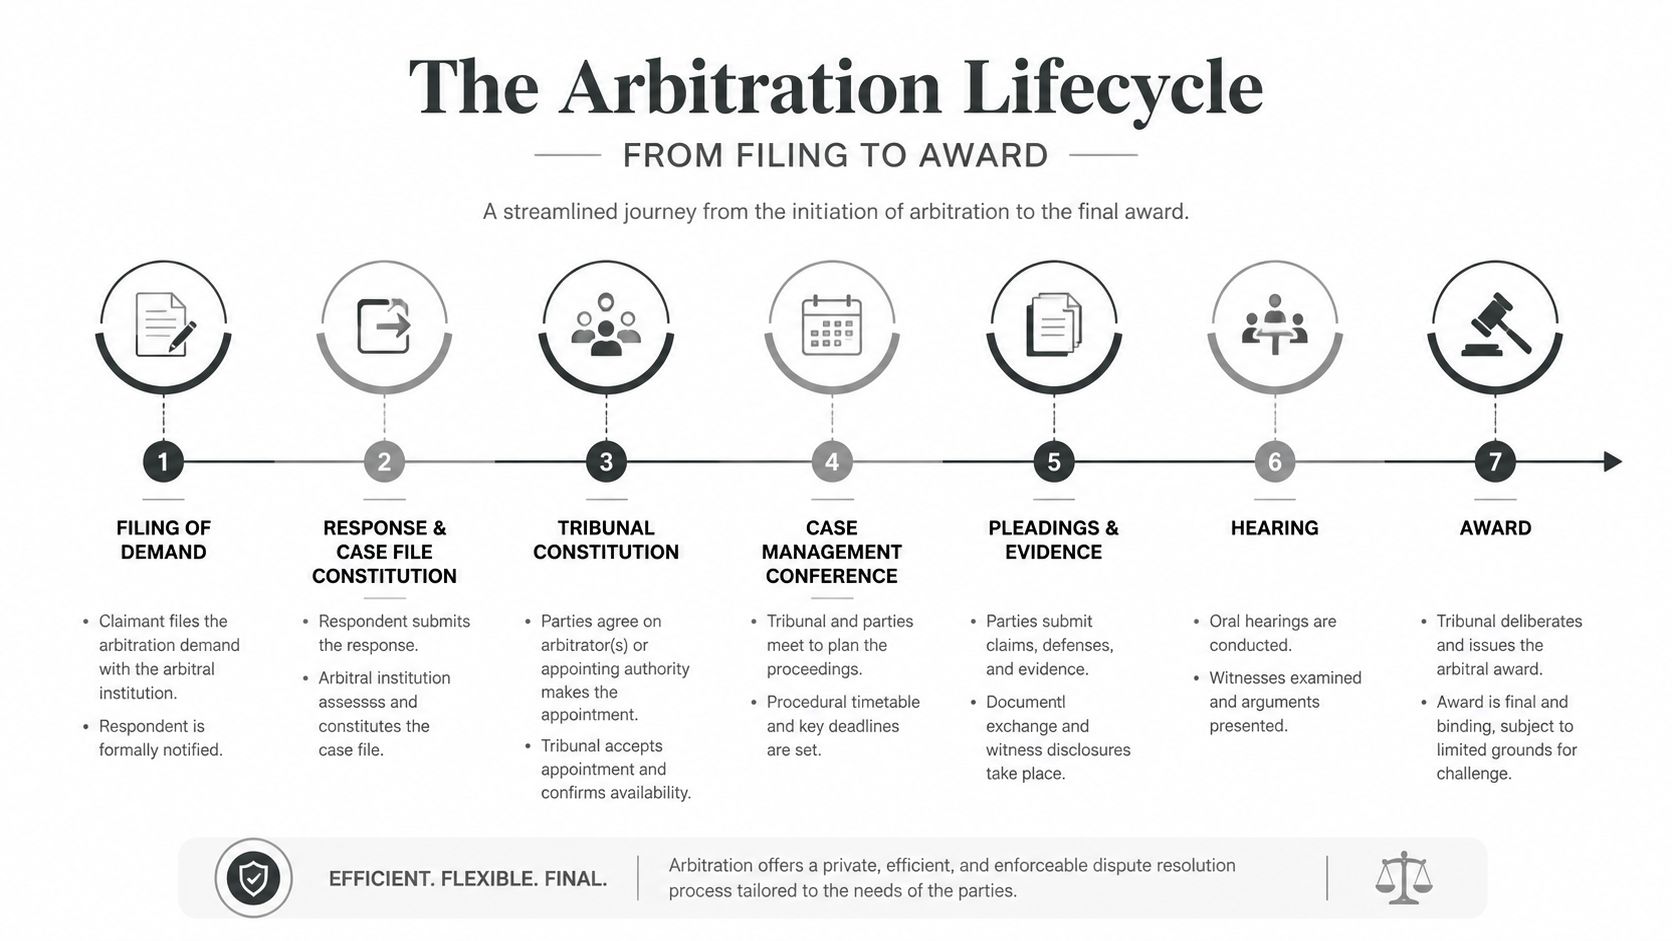
A strong arbitration usually begins before the statement of claim. Counsel should first identify the parties, agreements, account history, relevant dates, potential witnesses, and available remedies. Account statements and trade confirmations should be organized chronologically, while emails and messages should be preserved in their original form where possible.
The claimant then prepares a Statement of Claim that identifies the parties, factual allegations, legal theories, damages, and requested relief. The respondent answers, asserts defenses, and may bring counterclaims. A pleading that is too general can make damages and proof harder to present, while one that includes every conceivable theory can obscure the central dispute.
Early case management
FINRA discovery is compressed and rule-bound. Under FINRA Rule 13506, discovery requests generally cannot be served until 45 days after the statement of claim is served. Under the customer case code, document and information requests generally must be served within 30 days from the date the last answer is due, and responses or objections are generally due within 10 days of receipt.
Those windows make early collection essential. The relevant record may include account statements, emails, Form U5 materials, production-credit reports, compensation plans, supervision records, and internal compliance communications. A party that waits until discovery opens may discover that key records are difficult to retrieve or that the panel views the delay unfavorably.
FINRA guidance recommends setting the discovery cutoff close to the initial prehearing conference, with discovery-motion deadlines no more than three months after that conference. The panel may address document requests, depositions, subpoenas, confidentiality, motions to dismiss, and hearing logistics during these early conferences.
Hearing and award
Arbitrator selection often uses a ranked-list process. The parties review proposed neutrals, strike those they cannot accept, and rank the remaining candidates. A claim's size and requested relief can determine whether the panel has one arbitrator or three. Under FINRA's current customer-arbitration notice, a three-arbitrator panel is used when the claim exceeds $100,000, the amount is unspecified, or non-monetary relief is requested, unless the parties agree in writing to one arbitrator. Claims of $50,000 or less proceed under simplified arbitration before one arbitrator, while claims over $50,000 up to $100,000 may use three arbitrators if both sides agree in writing.
At the hearing, each side presents exhibits, direct testimony, cross-examination, stipulations, and legal argument. The panel then issues an award. Courts generally enforce awards unless a recognized statutory basis for vacatur applies, such as corruption, serious misconduct, or conduct exceeding the arbitrators' powers. Confirmation and enforcement ordinarily proceed through a United States district court when voluntary payment does not occur.
Common Causes of Action in Securities Arbitration
Customer claims and intra-industry disputes often share a forum but not a theory of liability. The investor typically focuses on account activity, product risk, disclosure, and loss. The advisor or broker may focus on employment promises, compensation records, supervisory actions, termination language, or the consequences of a Form U5.
Customer theories may include suitability under FINRA Rule 2111, material misrepresentations or omissions under Rule 2210 and Section 10(b) of the Exchange Act, churning, unauthorized trading, failure to execute, negligence, breach of fiduciary duty, and selling away under Rule 3280. Each theory requires a different evidentiary showing. A suitability claim may turn on investor profile, product characteristics, and recommendation history. An unauthorized-trading claim often turns on authority, order records, communications, and whether the customer ratified the transaction.
Churning requires proof that activity was excessive in relation to the customer's objectives and account. Misrepresentation claims require careful attention to what was said, when it was said, whether it was material, and whether the claimant relied on it. A general allegation that an investment performed poorly doesn't establish every legal theory.
Industry disputes bring a different record. Form U5 defamation and wrongful termination claims may depend on the accuracy, context, and publication of the disclosure. Promissory note and forgivable-loan cases turn on the contract, repayment triggers, termination circumstances, and credits or offsets. Deferred compensation, promissory estoppel, and production-credit disputes usually require compensation plans, payout reports, emails, and testimony from supervisors or payroll personnel.
Registered representatives may also assert compensation claims under applicable FINRA rules, including disputes involving the payment of remuneration. Expungement requests require compliance with the applicable FINRA procedures, including the requirements associated with Rule 13805. Some conduct can support parallel proceedings, such as a FINRA filing and a separate AAA claim, but parallel litigation creates cost, consistency, and preclusion risks.
| Cause of Action | Claim Type | Key Elements | Typical Defenses |
|---|---|---|---|
| Unsuitable recommendation | Customer | Recommendation, investor profile, product risk, causation, damages | Product was suitable, customer knowledge, market loss |
| Misrepresentation or omission | Customer | Material statement or omission, reliance, falsity, loss causation | Disclosures, no reliance, accurate risk disclosure |
| Churning | Customer | Excessive trading, control, intent or reckless conduct, loss | Customer control, legitimate strategy, no excessive activity |
| Unauthorized trading | Customer | Trade without authority, account loss, causation | Authorization, ratification, customer instructions |
| Form U5 defamation | Industry | False statement, publication, applicable privilege, harm | Truth, opinion, privilege, accurate reporting |
| Compensation or promissory note | Industry | Contract, payment or repayment obligation, breach, damages | Contract language, offsets, termination trigger |
| Expungement | Industry | Procedural eligibility and grounds for relief | Inadequate proof, public-interest concerns, procedural defects |
Investors should distinguish ordinary market loss from allegations of fraud or misconduct. A practical discussion of the difference appears in this explanation of securities fraud.
Damages, Costs, Fees, and Settlement Leverage
A damages demand should be built from a transparent method, not a round number chosen for negotiation. The analysis may include out-of-pocket loss, lost market opportunity, transaction-related costs, interest, and other legally recoverable amounts. The correct measure depends on the claim. An unauthorized-trading analysis may compare the account's actual result with what would have happened absent the trade, while an unsuitable-investment analysis may require a more careful comparison of the recommended strategy with a suitable alternative.
Statutory claims can carry remedies beyond common-law damages, depending on the statute and the facts. Interest may also be requested under applicable rules, including FINRA Rule 12514. Attorneys' fees aren't automatically awarded merely because a claimant wins. Recovery may depend on a contract, statute, sanction order, or another recognized basis.
The cost stack requires its own budget. Parties may face filing fees, member surcharges, hearing-session fees, arbitrator compensation, expert expenses, transcript costs, travel, and counsel fees. The applicable forum's fee schedule and the panel's orders determine the actual exposure.
| Cost Component | Who Pays | Approximate Range | Recovery Potential |
|---|---|---|---|
| Filing fee | Usually claimant at filing, subject to forum rules | Depends on forum and claim type | May be included in award if legally or contractually supported |
| Administrative surcharge | Often allocated under forum rules | Depends on administrator and case | Potentially recoverable if awarded |
| Hearing-session fee | Allocated by forum or panel | Depends on sessions and forum | May be shifted by agreement, rule, or award |
| Arbitrator compensation | Usually shared or allocated under forum rules | Depends on arbitrator and hearing structure | Not automatically recoverable |
| Attorneys' fees | Each side generally pays its own initially | Depends on counsel and complexity | Recoverable only where authorized |
| Expert and transcript costs | Usually incurred by the party using them | Depends on scope | May be awarded as costs in appropriate cases |
Settlement often makes economic sense when liability is uncertain, collection is a concern, or a hearing would expose sensitive employment or customer information. Mediation can occur before discovery is complete, after an exchange of core documents, or near a scheduled hearing. A contingent settlement structure may allow payment over time, but it should address default, releases, confidentiality, tax treatment, and whether any Form U5 or expungement relief remains outstanding.
Settlement is not automatically the superior result. A respondent may value a mutual release and finality, while an advisor may place greater value on corrected industry records. An investor may accept less than the demand if payment is prompt and collectible. The best advantage comes from a credible damages model, organized proof, and a realistic assessment of what the panel can award.
Practical Checklists for Claimants and Respondents
A claimant should begin with preservation, not accusation. Download account records, save communications, identify witnesses, and write a factual timeline while memories remain fresh. Then determine whether the dispute belongs in FINRA, AAA, JAMS, court, or another forum, and evaluate the eligibility and contractual deadlines before sending a demand.
Claimant priorities
- Preserve the account record: Keep statements, confirmations, correspondence, disclosures, notes, and electronic communications.
- Separate transactions from theories: Identify which trades support unauthorized trading, suitability, churning, misrepresentation, or another claim.
- Build damages early: Use a consistent methodology and identify assumptions that the respondent will challenge.
- Protect the filing position: Review the controlling agreement and FINRA eligibility rule before negotiations consume available time.
- Choose counsel carefully: A lawyer should understand both securities products and the procedural rules of the selected forum.
Respondent priorities
A respondent should secure the Form U5 history, employment agreement, compensation plans, customer agreements, supervisory records, compliance files, communications, and production-credit data. The defense should also identify documents that could undermine an overbroad denial, because credibility problems can affect settlement positioning even when the legal defenses are substantial.
- Test jurisdiction and eligibility: Determine whether the clause applies and whether the claim is timely.
- Audit the record: Compare the claimant's allegations with account activity, instructions, disclosures, and internal reports.
- Assess counterclaims: Promissory notes, repayment obligations, and compensation advances may affect the net value of the dispute.
- Consider mediation: A negotiated release may be more valuable than a costly hearing, particularly when employment records or future registration are involved.
- Preserve consistent positions: Statements in arbitration should not conflict with regulatory responses, Form U5 explanations, or prior correspondence.
| Action Item | Claimant | Respondent |
|---|---|---|
| Agreement review | Identify forum, governing law, waivers, and remedies | Confirm coverage, defenses, and counterclaim rights |
| Evidence preservation | Secure account and communications records | Secure compliance, employment, and U5 records |
| Damages | Prepare transaction-level calculation | Test assumptions, causation, and offsets |
| Discovery planning | Request documents tied to each claim | Object precisely and produce defensible records |
| Settlement | Value money, timing, confidentiality, and corrective relief | Value release, cost control, and reputational protection |
| Hearing preparation | Organize witnesses and exhibits around the theory | Prepare cross-examination and alternative explanations |
People who aren't sure whether they need securities counsel, employment counsel, or commercial litigation advice can use a website that helps match you with a lawyer as an initial orientation tool. The match should still be followed by direct questions about FINRA experience, forum-specific practice, conflicts, fees, and the lawyer's role in the dispute.
Why Strategy Beats Forum and What's Next
The forum matters, but it rarely rescues a poorly framed case. FINRA, AAA, and JAMS each offer different rules and administration, yet the outcome often turns on earlier decisions: which documents were preserved, how the claim was calculated, whether the right parties were named, and whether the first discovery requests targeted the facts that prove liability.
Securities arbitration also serves two distinct populations. Investors may seek recovery for account conduct or product-related losses. Advisors and brokers may need protection from inaccurate Form U5 language, unpaid compensation, promissory-note claims, wrongful termination, or related employment disputes. Each requires counsel who understands the role-specific record.
Before filing, seek advice on eligibility, forum selection, damages, discovery, and settlement authority. After an award, enforcement may require additional procedural work, as discussed in this guide to arbitration award enforcement.
If you want to discuss your business law matter, contact Kons Law at (860) 920-5181. Kons Law handles securities arbitration and related business disputes for investors, advisors, and financial professionals, helping clients evaluate the merits, timeline, evidence, and cost of arbitration versus other available paths. Visit Kons Law to request a consultation.
